
On “girl math,” lifestyle inflation, and why our 20s can make spending feel like a personality trait.
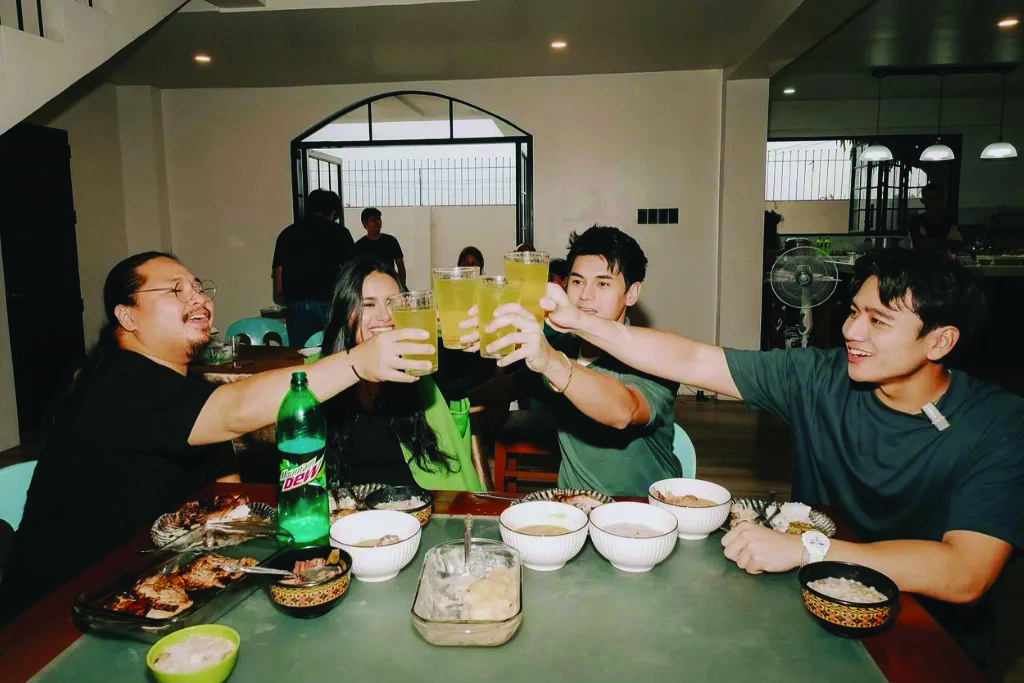
There’s a very specific experience of being in a person’s 20s right now: Open TikTok for 5 minutes and save posts about a restaurant in Makati, a new café in BGC added to the weekend plans, three outfits suddenly needed, and a slideshow informing the possible entry to dozens of countries sans a visa.
The algorithm is generous like that. There is always somewhere to go, something to eat, or somewhere to travel to. A new matcha place appears. A “hidden gem” is no longer that because hundreds of thousands of people have already saved the video. Concerts need tickets. Skincare drops need trying. Airline promotions arrive with the urgency of a financial emergency.
Then there is the money: A P500 coffee is expensive unless it is a reward for surviving the workweek. A P3,000 dress doesn’t really cost that much if worn multiple times. A concert ticket is an “experience,” so surely it cannot count as unnecessary spending. Something bought on sale is practically saving money.
This is “girl math”: the online joke that became popular on TikTok in 2023. It uses a deliberately gendered label, but the spending logic behind it is hardly exclusive to women. It describes the deliberately illogical calculations people use to justify spending. Cash apparently counts differently from money in a bank account. A discount becomes “savings.” An expensive purchase can be broken down into a cost-per-use figure until it starts looking reasonable. It is funny because it is familiar.
Beneath the joke, however, is a real concept in behavioral economics: mental accounting. This refers to the tendency to divide money into separate mental categories and treat those categories differently. Researchers have found that these mental categories can influence how people spend and save.
“Girl math,” then, is not really mathematics—it is an “Internet-friendly” way of showing how easily we can convince ourselves that a purchase makes sense.
For people in their 20s, that matters because money often starts feeling different then. An allowance becomes a salary. A first job means being able to pay for things without asking anyone first. A promotion can mean a better phone, a nicer apartment, or finally booking the trip sitting in your
saved folder.
Then comes the second paycheck… The third… The raise… Suddenly, things that used to feel like treats begin to feel normal. That is where lifestyle inflation enters the picture.
AFFORDABILITY BECOMES BASELINE
Lifestyle inflation, sometimes called “lifestyle creep,” happens when spending increases alongside income.
It is not necessarily a bad thing. Earning more can reasonably mean better food, housing, transportation, or travel. The problem starts when every income increase automatically leads to higher spending.
Consider employees earning P25,000 a month. They learn to survive on that amount. They commute, bring lunch from home, and think twice before shopping. Then they receive a raise to P35,000.
The additional figure could go toward savings, debt payments, or a better quality of life. Instead, it slowly disappears into a more expensive version of the same life. More Grab rides… More meals outdoors… And more weekends out…
Nothing dramatic happened. That’s the point.
Lifestyle inflation rarely announces itself. It arrives as tiny upgrades that eventually become permanent.
Coffee has now become a weekday habit… Food delivery becomes the default after a long day. The P1,000 dinner becomes “just what we spend when we go out.” A once-a-year trip becomes an annual expectation.
This is where “girl math” gets interesting. The joke is about finding a reason a purchase doesn’t really count. Lifestyle inflation is what happens when enough of those purchases start counting as normal. The joke may have a gendered name, but the underlying behavior is broader. Anyone can turn a one-off indulgence into a recurring expense once it becomes part of their idea of a normal lifestyle.
There is an important difference between being able to afford something, and being able to afford the lifestyle that comes with it. A P700 dinner may be affordable once. Having P700 dinners four times a week is a different calculation. The problem is rarely one isolated purchase. It is repetition.
This is why financial literacy cannot stop at knowing how to calculate interest or understand a bank product. It also requires noticing where money goes and which expenses have quietly become non-negotiable.
The Bangko Sentral ng Pilipinas’ 2025 Consumer Finance and Inclusion Survey found that 74% of Filipino adults could correctly answer at least half of six financial-literacy questions. That was up from 69% in 2021. At the same time, 86% reported having a personal budget, while only 43% said they were satisfied with their current financial situation.
That gap is worth noting. Awareness that budgeting is a must isn’t the same as feeling financially secure. One can understand compound interest and still spend P400 on delivery because it is too tiring to cook; or know that saving matters, and still be convinced that this month’s concert ticket is
“an experience.”
Financial literacy does not make us immune to being human.
PSYCHOLOGY BEHIND THE JOKE
One reason “girl math” works so well is that people do not experience money as purely numerical.
For instance, a P2,000 dinner is not just P2,000. It might be a birthday dinner or the only free evening you have had in three weeks. A P4,000 pair of shoes might be something needed for work. A P1,500 skincare haul might be framed as self-care.
The meaning attached to a purchase changes how it feels.
This is where mental accounting comes in. Richard Thaler’s work in behavioral economics showed that people often mentally divide money into different “accounts” instead of treating every peso as interchangeable. Money received unexpectedly, such as a bonus, refund or gift, may feel easier to spend because it has not already been assigned to rent, food or bills.
That is essentially the academic version of “girl math.” The Internet version simply packages a familiar human behavior into a catchy,
gendered joke.
There is nothing inherently wrong with having different spending categories. Mental budgeting can actually be useful. Setting aside money for necessities and entertainment can make finances easier to manage.
The problem comes when the category becomes an excuse. A refund becomes “free money.” Cash becomes “not real money.” A discount becomes “saving.” A credit-card purchase becomes “next month’s problem.” The numbers have not changed. Only the story has.
SALES DO NOT NECESSARILY SAVE
Consider one of the most popular forms of Internet financial logic: the sale.
A P5,000 item is marked down to P3,500. Congratulations! That could be P1,500 in savings. The thing is, there wasn’t even P5,000 to begin with. P3,500 was spent.
If you already wanted the item and had budgeted for it, the discount may have improved the deal. If the sale convinced you to buy something you otherwise wouldn’t have purchased, the discount didn’t save you money; it gave you a reason to spend.
The same applies to “cost per use.” A P6,000 jacket worn 20 times costs P300 per wear. That calculation can be useful when comparing products. It does not change the fact that P6,000 is left in the bank.
Behavioral economists have long studied how framing affects financial decisions. Even the way a price is presented can change how people perceive its value.
“Girl math” is essentially framing—with a sense of humor. The danger is not doing the calculation. The danger is doing it only until you have the answer you want.
ALGORITHM HAS A SHOPPING LIST
Another reason lifestyle inflation feels particularly relevant to this generation: It is constantly being bombarded with things to spend money on.
A TikTok post about a café becomes a weekend itinerary. A “things to do in Manila” video becomes a list of expenses. A travel creator posts a carousel of visa-free destinations for Filipinos. A country outside the radar suddenly settles on a five-year plan.
A “day in my life” video can casually include coffee, Pilates, lunch, skincare, shopping and dinner.
Individually, none of these things seems unreasonable. Together, they can create a lifestyle that costs much more than you realize.
We are not necessarily comparing ourselves with celebrities anymore, but with people who look like us: people our age, people working in the same city, and people with the same five-day workweek.
Their lifestyles therefore feel achievable.
When enough people online appear to be eating at the same restaurants, traveling to the same countries and buying the same things, consumption can start to look less like consumption, and more like participation.
The problem is that social media shows purchase, not financial context.
We see the airport outfit, not the credit-card statement. We see the hotel room, not the savings plan. We see the “little treat,” not the cumulative cost of having one every day.
Research on young adults entering the workforce reinforces the idea that financial behavior is shaped by more than financial knowledge. A 2026 study of young Australian adults identified different financial-habit groups and found that normative beliefs and perceived control helped shape financial habits alongside financial literacy.
Knowing better is only part of the battle. What feels normal around us matters, too.
THE SALARY: NOT A SPENDING TARGET
One useful habit to develop in your 20s is separating income growth from lifestyle growth.
A raise does not have to become a new expense. If a salary increases by P5,000, spend some of it, save some of it, invest some of it, use some to pay debt, or help the family. There is no universal formula because financial circumstances differ.
The point is to decide before a lifestyle dictates. Otherwise, every raise simply raises the cost of being one’s self.
This matters because income may grow while responsibilities rise too. Rent can increase. Families may need support. Careers can change. Emergencies happen.
If every increase in income has already become a permanent monthly expense, cutting back later becomes much harder.
If some of that income growth has gone toward savings or other financial goals, there is room to move. Financial security is, in part, the ability to
have choices.
THE PRESENT VS. THE FUTURE
There is also a psychological reason saving can lose to dinner reservations.
The dinner happens now. The emergency fund is for later. The trip gives you something to look forward to. Retirement belongs to a version of you that is difficult to imagine.
This relates to present bias: the tendency to weigh immediate rewards more heavily than future benefits. Research has linked stronger present bias with greater spending and borrowing and lower saving.
This is why financial systems can be more effective than relying on willpower. Automatic savings transfers, separate accounts for specific goals, and waiting periods for expensive purchases can reduce how often you have to negotiate with yourself.
Sometimes the problem isn’t knowing what to do. It is that TikTok just showed a restaurant that’s really worth trying.
ROOM TO ENJOY A LIFE
Some versions of financial literacy treat enjoyment as the enemy: Don’t eat out, don’t buy coffee, don’t travel, and don’t shop until some imaginary state of financial perfection is reached. That is not particularly realistic.
Money is supposed to support a life—not merely sit untouched in an account. A budget can include restaurants. It can include concerts and travel. It can include clothes, hobbies and coffee.
The difference is that these things should have a place in the plan.
Allocate P3,000 for entertainment and spend P1,500 on a concert. There, a decision has been made. If you bought a ticket and hoped there was enough left for everything else, you’ve arrived at a different kind of decision.
The goal isn’t to eliminate treats; it is to make sure every treat doesn’t become a recurring expense disguised as a necessity.
BETTER GIRL MATH?
There is nothing inherently wrong with “girl math.” It is funny because most of us have done some version of it.
We have justified a purchase because it was on sale. We have divided the price by how many times we expect to use something. We have mentally placed money into a “this doesn’t
count” category.
The joke becomes useful when it makes us notice those habits.
Maybe the better version of girl math is asking whether you would still buy something at full price. It may be considering the actual cost of a purchase made with points or cashback. It may be asking whether you have room in your budget for the upfront cost, rather than just calculating cost per wear.
When a raise arrives, decide how much to allocate for lifestyle. Most importantly, “I can afford it” should not automatically mean “I should buy it.” That is the real antidote to lifestyle inflation. The expensive part of a lifestyle is rarely one purchase, but the lifestyle itself.
A café visit becomes a weekly ritual… A weekend trip becomes an annual expectation… Delivery becomes routine… Convenience becomes standard… The things that once felt luxurious quietly become things you feel entitled to have.
There is nothing wrong with wanting more when earning more. The trick is to ensure “more” is actually what you want.
Maybe it is better coffee…. Or traveling while still young… Living closer to work… Helping the parents… Having enough savings to leave a miserable job… Those are all different definitions of financial progress.
Being in one’s 20s doesn’t need to be a decade of deprivation in the name of some perfectly optimized future. It doesn’t have to become a decade where every raise is immediately converted into a more expensive version of the same life.
Know all about the newest café, the next concert, the best restaurant in town, or the latest visa-free destination… Just find where the balance is, too.
Perhaps the smartest version of “girl math” isn’t about finding a clever reason to spend P5,000. It is knowing it can be spent, knowing what you give up by spending it, knowing what the rest of the money needs to do, and deciding the P5,000 is still worth it.
Hjadoeya Calica
Hjadoeya Calica is a cinephile, reader, and a content writer for Philippines Graphic whose roots trace back to La Union and Aurora. She studied AB Literature at the University of Santo Tomas where she served as the Literary Editor for The Flame. Currently based at the heart of Makati, she finds inspiration in stories of every kind, spaces, and places.